Generational wealth extends far beyond a simple inheritance. It represents the long-term accumulation, protection, and transfer of assets, knowledge, and opportunities from one generation to the next. When families plan thoughtfully, they build a foundation that not only safeguards financial resources but also fosters values, skills, and habits that last a lifetime.
In this article, we explore the definition, importance, and practical steps to create a legacy that endures. From understanding key statistics to addressing systemic gaps, you’ll discover how both modest and significant transfers of wealth can empower future generations.
What Is Generational Wealth?
Generational wealth refers to the total value of assets accumulated by one generation and passed on to descendants. Unlike income, which is earned and consumed, wealth represents the value of assets minus debts. When structured properly, generational wealth can benefit family members for decades.
- Cash and savings
- Investment accounts and securities
- Retirement assets
- Real estate and home equity
- Businesses and ownership interests
- Life-insurance proceeds
- Trust assets
- Valuable personal property
- Intellectual property
- Educational opportunities and social capital
It’s crucial to distinguish between:
• Income: money earned through work or investments.
• Wealth: net asset value.
• Generational wealth: assets structured to outlive their original owner.
Why It Matters
Building generational wealth unlocks possibilities that transcend immediate survival. Families with a robust financial foundation can:
- Purchase homes and build equity
- Fund quality education
- Start or expand businesses
- Absorb emergencies without high-interest debt
- Make long-term lifestyle decisions free from financial stress
This self-reinforcing nature means assets generate income, appreciate in value, and open doors to further opportunities. A strong base today can multiply into a lasting legacy tomorrow.
Key U.S. Wealth Statistics
Wealth disparities in the United States reflect historical and structural factors. According to the 2022 Federal Reserve Survey of Consumer Finances:
While Black and Hispanic households saw faster percentage growth after the Great Recession, the absolute wealth gap remains large. The top 10% of households hold roughly 74% of total wealth, underscoring the concentration of assets among the wealthiest.
Beyond Large Inheritances
Many assume generational wealth only arrives via multimillion-dollar inheritances. In reality, most transfers are modest yet impactful. Between 1995 and 2016:
- 55% of inheritances fell below $50,000
- Only 2% exceeded $1 million, accounting for over 40% of transferred wealth
- Small gifts often cover education costs or emergency expenses
Even a modest transfer—a down payment gift, tuition assistance, or emergency loan—can prevent high-interest debt and accelerate wealth building for recipients.
Bridging Historical Gaps
Wealth disparities are not solely the result of personal choices. They stem from long-standing differences in access to homeownership, credit, education, and business financing. Home equity, in particular, has driven middle-class wealth for decades. Variations in mortgage availability, neighborhood appreciation, and tax policy compounded these gaps.
Research suggests intergenerational transfers explain 12%–16% of the racial wealth gap. This reveals a dual truth: while strategic planning matters, starting conditions matter profoundly. A balanced approach recognizes systemic barriers and empowers families to navigate them.
Major Pillars of Building Generational Wealth
Successful legacy planning combines financial stability and disciplined investment with intentional knowledge sharing. Key pillars include:
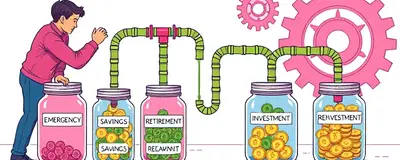
Establish Financial Stability: Begin with a realistic budget, an emergency fund, and management of high-interest debt. Protect assets with insurance and set clear financial goals. An emergency reserve prevents forced asset sales during crises.
Invest Consistently Over Time: Harness compounding returns through diversified portfolios. Utilize tax-advantaged accounts like retirement plans and education savings. Maintain an asset mix aligned with your risk tolerance and time horizon.
Build Home Equity Carefully: Consider a primary residence or rental property as a wealth-building tool. Weigh mortgage terms, maintenance costs, taxes, and market risk. Avoid becoming “house poor” by ensuring housing remains affordable.
Start, Buy, or Grow a Business: A family enterprise can create significant equity and income. Address legal structure, accounting, and succession planning early. Mitigate key-person risk with buy-sell agreements and leadership development.
Formalize Transfer Plans: Use wills, trusts, and beneficiary designations to clarify asset distribution. Establish guardianship arrangements for minors and philanthropic vehicles if charitable giving is a priority.
Teach the Next Generation: Share financial knowledge, values, and decision-making frameworks. Encourage budgeting, investing basics, and long-term goal setting. A well-informed heir is better equipped to steward inherited assets responsibly.
Generational wealth is more than a monetary gift—it’s a combination of resources, wisdom, and opportunity that empowers families to thrive. By understanding disparities, adopting proven strategies, and fostering open financial communication, you can build a legacy that endures.