Embarking on a mortgage hunt can feel overwhelming, but securing a pre-approval transforms uncertainty into clarity. With a pre-approval letter in hand, borrowers gain insight into their financing potential before they start house-hunting.
Understanding Pre-Approval
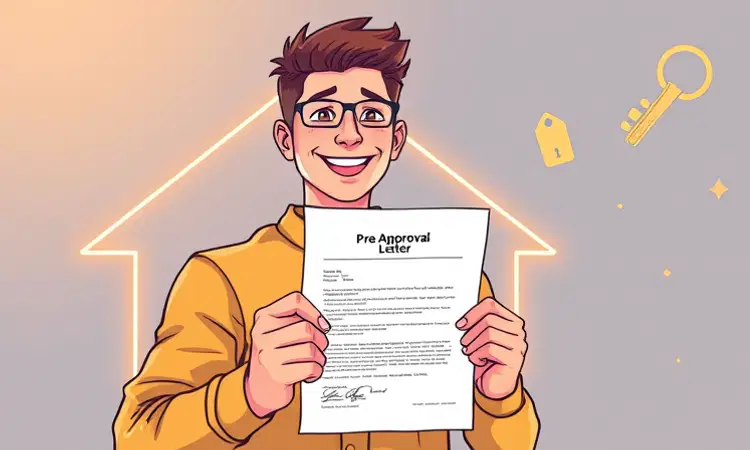
A mortgage pre-approval is a written statement from a lender indicating the maximum loan amount you may qualify for, based on a review of your financial records. This process goes beyond a simple estimate, requiring verification of income, assets, debts, and credit history.
While a pre-approval offers a conditional indication of the amount you can borrow, it is not a guaranteed loan approval. Final loan approval still hinges on factors such as property appraisal, title checks, and a consistent financial profile at closing.
Pre-Approval vs Prequalification
Consumers often confuse prequalification with pre-approval, but the two serve different purposes. Prequalification is a quick estimate, while pre-approval is a more in-depth assessment that demands documentation. Understanding the distinction can save time and prevent surprises down the line.
Because terminology can vary among lenders, always inquire whether there was a credit pull, which documents were verified, and how long the pre-approval letter remains valid.
It Establishes a Realistic Purchase Budget
Armed with pre-approval, you move from guesswork to certainty about your borrowing limit. This clarity allows you to narrow your search to homes within reach and avoid disappointment when discovering properties outside your price range.
Even so, your maximum loan amount should not define your comfort zone. Account for taxes, insurance, maintenance, and personal expenses to create a realistic and sustainable personal budget that aligns with your lifestyle goals.
It Strengthens Buyer Credibility
In competitive real estate markets, sellers prioritize offers backed by financial readiness. A pre-approval letter signals seriousness and demonstrates that you have undergone a meaningful review of your finances.
Presenting a pre-approval can strengthen your offer in competitive markets, setting you apart from buyers who delay lender consultations until after their offer is accepted.
It Makes Your Offer More Competitive
Beyond credibility, sellers gain confidence that your transaction is less likely to collapse due to financing issues. While price and contingencies matter, pre-approval addresses the critical concern of closing certainty.
Keep in mind that a strong pre-approval complements—but does not replace—a solid offer structure, which includes an appropriate purchase price, earnest-money deposit, and reasonable inspection terms.
It Identifies Problems Early
Submitting documentation during pre-approval often uncovers undisclosed issues—such as high debt ratios, missing income documentation, or credit-report errors—long before you find a home. Early detection means you have time to address concerns.
You can identify financial problems early on and take corrective action, whether that means paying down debt, correcting credit mistakes, or building larger reserves for closing.
It Speeds Up the Application Process
Because lenders review much of your financial profile during pre-approval, the final underwriting stage can proceed more smoothly. Although further documentation is still required, having a pre-approval in place can reduce repeated document requests and keep your timeline on track.
It Enables Smart Comparison Shopping
Engage with multiple lenders to compare interest rates, fees, and loan programs. The Consumer Financial Protection Bureau recommends obtaining pre-approval from at least three institutions to ensure you secure the most favorable terms.
A refined shopping approach empowers you with a comprehensive comparison of loan options, allowing you to weigh not just rates but total cost, underwriting standards, and communication quality.
The Four Cs of Lender Assessment
Lenders commonly evaluate your loan application based on the “Four Cs.” Understanding these factors can help you strengthen your profile before applying.
- Capacity – Your income, employment stability, and debt-to-income ratio.
- Capital – Down payment funds, savings, and reserves for closing.
- Collateral – The home’s value, condition, and eligibility as loan security.
- Credit – Your credit history, score, and outstanding obligations.
Documents You May Need
Pre-approval requires detailed records. While specifics vary by lender and financial complexity, common documents include:
- Government-issued identification.
- Recent pay stubs and W-2 forms.
- Federal tax returns and bank statements.
- Investment account summaries.
- Proof of down payment and reserve funds.
Questions to Ask Your Lender
Clarify the scope of your pre-approval by asking:
- Which documents were independently verified?
- Was my credit pull hard or soft?
- Is the quoted rate locked or estimated?
- What conditions remain before final approval?
- How long does the pre-approval letter last?
Securing a mortgage is a journey filled with critical milestones. Pre-approval acts as a compass, guiding you with financial confidence and strategic insight.
By understanding the process, gathering the right documents, and engaging multiple lenders, you position yourself as a formidable buyer and pave the way for a smoother closing experience. Embrace the power of pre-approval and step into homeownership with clarity and conviction.