Life is full of surprises—some of them costly. A well-stocked emergency fund serves as a financial lifeline when the unexpected strikes, helping you avoid high-interest loans or raiding retirement savings.
Whether it’s a sudden job loss, a major car repair, or an unanticipated medical bill, having cash on hand can transform a crisis into a manageable setback. This guide will walk you through every step of creating and growing that essential buffer.
Why Emergency Funds Matter
Unexpected expenses are more common than most people realize. In 2025, 59% of U.S. adults experienced at least one major surprise cost in a year. Without savings, many households turn to credit cards or personal loans, trapping them in a cycle of debt.
An emergency fund shields you from financial shocks such as:
- Major vehicle repair or replacement (30%)
- Home or appliance repairs (22%)
- Unexpected medical expenses (21%)
- Job loss or reduced work hours
- Urgent travel or pet-care costs
By covering these costs with cash, you avoid relying on high-interest debt and maintain control of your finances.
Defining an Emergency Fund
An emergency fund is cash set aside for unplanned necessary expenses or income loss. Its primary qualities are:
- Liquid and accessible quickly without selling investments.
- Stable, avoiding significant market swings.
- Separate from everyday checking to reduce temptation.
- Low-risk, designed to preserve principal.
Common homes for your emergency savings include federally insured high-yield savings accounts, money market deposit accounts, or short-term savings accounts earmarked for emergencies. The top priority is security and accessibility, not maximum return.
How Much Should You Save?
Your target emergency-fund amount equals your essential monthly expenses times desired coverage months. For example, with $2,400 in monthly essentials:
- One month: $2,400
- Three months: $7,200
- Six months: $14,400
Experts commonly recommend three to six months of essential expenses. To make saving less daunting, start with a smaller goal—often between $500 and $1,000—before building toward your long-term target.
Starting with a clear, attainable milestone helps build momentum. Once you reach the first layer, you can shift focus to expanding coverage.
Calculating Essential Expenses
Essential expenses are costs you cannot eliminate during a crisis. These typically include:
rent or mortgage, utilities, basic groceries, insurance premiums and deductibles, transportation and fuel, car payments, minimum debt obligations, required tuition, essential medications, phone service, and pet necessities. Tracking one month of spending, categorizing each cost, and totaling essentials creates a realistic baseline.
Avoid underestimating by using realistic crisis spending levels. You may cut back on dining out, but you cannot eliminate insurance or necessary childcare without severe hardship.
Choosing the Right Target
Deciding between three and six months depends on your personal situation. Three months may suffice if you have stable employment, low fixed expenses, strong insurance coverage, and a dual-income household. However, if you face single income, high mortgage costs, seasonal pay, or limited family support, aim for six months or more.
Protecting against prolonged income gaps often means erring on the side of caution, particularly for freelancers, commission-based earners, or those in high-risk industries.
Building Your Emergency Fund Step by Step
Establishing a fund requires consistency, discipline, and clear rules. Follow these steps:
- Define a written purpose for the account to reduce impulse withdrawals.
- Calculate your monthly essentials and set a realistic initial target.
- Automate regular transfers from checking to your emergency account.
- Review and adjust your budget to funnel more savings into the fund.
- Celebrate milestones to maintain motivation and momentum.
Even small, regular contributions compound over time. Automating deposits ensures progress continues uninterrupted by forgetfulness or competing priorities.
Integrating Into a Broader Financial Safety System
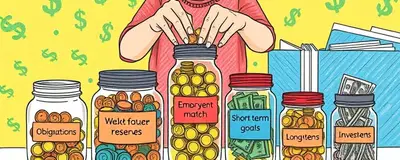
An emergency fund is one pillar of a comprehensive safety net. Complement it with adequate health, auto, homeowners or renters, disability, and life insurance; responsible debt management; retirement savings kept distinct from short-term cash; income protection through skill development and networking; and clear legal planning such as powers of attorney and wills. Additionally, maintain separate sinking funds for predictable irregular costs like taxes, annual insurance premiums, or vehicle maintenance.
This layered approach ensures that predictable expenses are planned, freeing your emergency fund exclusively for true crises.
Maintaining and Replenishing Your Fund
Life changes—new home, growing family, career shifts—can alter your expense profile. Periodically review your target, especially after major milestones like purchasing a home or welcoming a child. If you tap into this fund, prioritize rebuilding by temporarily increasing contributions until you return to your previous coverage level.
Regular check-ins, such as quarterly budget reviews, keep your emergency fund aligned with your evolving needs.
Conclusion
Creating a robust emergency fund transforms uncertainty into confidence. By setting clear goals, automating savings, and integrating this fund into a broader financial safety system, you build resilience against the unexpected. Start small, stay consistent, and watch your financial safety net grow—one deposit at a time.