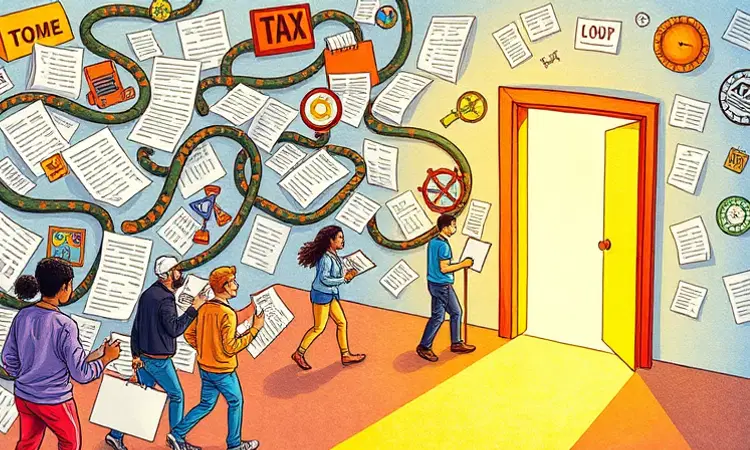
Tax complexity is both a policy-design problem and a user-experience problem. Taxpayers confront layers of rules, frequent changes, and multiple filing obligations. Administrations juggle goals of revenue, fairness, enforcement, and anti-avoidance. In this article, we explore how true simplification means reducing the time, uncertainty, cost, error risk, and friction involved in every stage of compliance, without compromising essential public goals.
Understanding the Tax Labyrinth
Tax systems become a maze for five main reasons, each adding its own challenges for taxpayers and administrators. Legislators and agencies must balance policy ambitions with everyday usability, yet complexity often compounds:
- Legislative complexity: Too many deductions, credits, exemptions, rates, thresholds, definitions, and exceptions.
- Administrative complexity: Separate registrations, forms, deadlines, portals, payment systems, and documentation requirements.
- Economic complexity: Multiple jobs, investments, businesses, international income, and digital-platform earnings.
- Temporal complexity: Frequent legislative amendments and shifting effective dates.
- Interpretive complexity: Technically precise rules that ordinary taxpayers find hard to understand.
The Scale of the Burden
In the United States, estimates reveal the immense toll of compliance:
These figures are estimates, not precise measures of every individual’s experience. Methodological differences account for variations: some analyses assign zero cost to certain forms, others omit indirect burdens like stress and delayed decisions. A reported decline from 7.93 to 6.93 billion hours between recent years may reflect methodological changes more than real simplification.
Why Tax Systems Become Complex
Several forces drive complexity in tax codes and procedures. Understanding these drivers helps target effective reforms.
Policy goals accumulate over time. Legislators use the tax code to pursue objectives that could otherwise be addressed through direct spending or regulation. Each incentive—home ownership credits, retirement-saving subsidies, clean-energy deductions, research-and-development allowances—requires eligibility tests, recordkeeping, phase-out limits, interaction rules, and anti-abuse safeguards.
Frequent legislative change adds “temporary complexity.” When rates, thresholds, or definitions shift annually, software updates, professional training, employer payroll revisions, and new agency instructions become essential. Taxpayers may delay filing while awaiting clarity. A reform principle is limiting retroactive changes and lead time for new provisions, reducing last-minute confusion.
Multiple taxes and government levels multiply obligations. Individuals and businesses may juggle:
- Personal income tax and payroll contributions
- Sales or value-added tax and customs duties
- Property tax, corporate tax, and withholding requirements
- Local, regional, and international filings
When agencies use different definitions, portals, deadlines, or ID systems, the administrative burden escalates.
Who Bears the Burden
Complexity does not fall evenly. Some pay the steepest price in time, money, and stress.
Individuals with self-employment income, multiple employers, investments, foreign assets, or digital-platform earnings face higher calculations and documentation requirements. Life changes—marriage, divorce, relocation, retirement—trigger new rules and potential errors.
Small businesses often lack in-house tax expertise. They must handle registration, bookkeeping, payroll, VAT or sales-tax filings, depreciation rules, employment classification, and local licensing. Complexity can deter formalization and shift focus away from growth, giving larger firms an advantage.
Low-income taxpayers struggle with refundable credits and benefits. They are vulnerable to overclaims, underclaims, or missed entitlements due to limited advice, unstable income, and digital access challenges. Simplification strategies must include plain-language instructions, automatic eligibility checks, and free filing support.
Women-led and informal firms often face arbitrary enforcement and ambiguous criteria. Simplified regimes should avoid assumptions that exclude home-based or mixed-activity businesses and ensure thresholds prevent subsistence firms from unintended obligations.
Tax professionals and intermediaries absorb complexity indirectly. Employers, accountants, payroll providers, and financial institutions update systems and interpret rules on behalf of taxpayers. A system may seem simple to the government but simply transfers costs to these actors.
Simplification Strategies for Taxpayers
While taxpayers cannot rewrite the tax code, they can adopt practices to limit unnecessary complexity.
Build a tax calendar. Track deadlines for registrations, estimated payments, and information returns. A personalized calendar reduces last-minute rushes and penalties.
Use digital tools and pre-filled returns when available. Many administrations offer portals that auto-populate income sources, withholding data, and reported credits. Reviewing and confirming entries takes far less time than manual data entry.
Organize documentation year-round. Maintain a simple filing system—physical or digital—for receipts, statements, and certificates. Regularly reconcile records against bank statements to catch discrepancies early.
Leverage free or low-cost assistance. Community organizations, libraries, and government programs often provide volunteers or online advice hubs. Early engagement can prevent errors and reduce professional fees.
Understand key definitions and thresholds. Familiarize yourself with the most relevant terms—dependent, business income, capital gain—and know where to find clear explanations. Official plain-language guides or taxpayer bulletins can clarify interpretive complexity.
Plan life events with tax impact in mind. Major changes—buying a home, starting a business, or changing employment—often have tax consequences. Consult a professional or use credible online calculators before making decisions.
Advocate for simplification. Join taxpayer associations or public consultations to share front-line experiences. Collective feedback helps administrations identify high-friction areas and design user-friendly forms and processes.
By adopting these steps and supporting well-designed reforms, both taxpayers and administrations can transform the tax labyrinth into a streamlined system that balances fairness, revenue goals, and ease of use.