In a world of budget apps and tracking spreadsheets, many households still find themselves stretched thin by expenses that seem minor in isolation. These often unnoticed small, recurring expenses can quietly weaken a household’s finances over time, undermining emergency savings and long-term goals without any dramatic purchase.
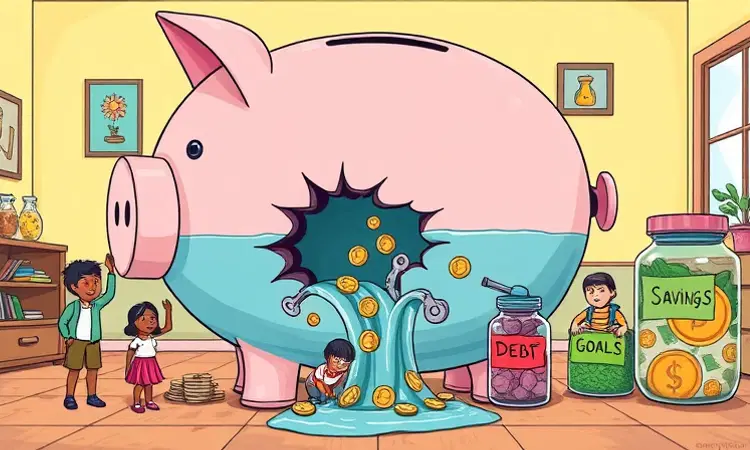
Rather than eliminating coffee runs or cutting out all entertainment, the focus here is on revealing and stemming those tiny drips of spending, then channeling the recovered money toward meaningful objectives like debt repayment or future investments.
Each month, those little charges accumulate stealthily, eroding your budget step by step. Ignoring them could lead to repeated overdrafts, surprise fees, or lost opportunities, while a quick audit often uncovers tens or even hundreds of dollars in potential savings.
Why Addressing Invisible Leaks Matters
Data from the Federal Reserve highlight the challenge. In 2025, only 55% of U.S. adults had enough savings to cover three months of essential expenses—unchanged from 2024 and below the 59% peak in 2021. Meanwhile, 26.5% of consumers paid overdraft and nonsufficient-funds fees in the past year, with per-item charges from $15 to $36. A single $35 fee can exceed the cost of several discretionary coffees or snacks.
A separate 2025 Bankrate survey found that 59% of Americans lacked enough savings to cover an unexpected $1,000 expense, and 27% reported having no emergency savings at all. These facts underscore how reclaiming modest sums can bolster resilience.
Maintaining a consistent cash flow surplus is critical. In 2024, 85% of adults who always had money left over at month’s end had at least three months of expenses saved, compared with just 13% of those who never had leftover funds. Tracking these metrics shows that small shifts in spending behavior can yield significant increases in financial security.
Identifying Your Spending Leaks
We define a spending leak as any recurring or repeated outflow that provides less value than its cost, is forgotten or underestimated, or could be reduced through a simple change. Leaks differ from responsible spending: they often slip by unnoticed and deliver no proportionate benefit.
By shining a light on these flows, you can decide which services truly deserve your wallet and which can be paused or cancelled altogether.
- Forgotten subscriptions and expired trials
- Convenience fees and small-order surcharges
- Impulse purchases online and in-store
- Food waste and unplanned restaurant orders
- Banking and financial service fees
- Price creep on auto-renewals
- Duplicate or overlapping service plans
- Buy-now-pay-later installment costs
Conducting a Simple Financial Audit
Performing a targeted audit can reveal where money silently drips away each month. Follow these steps to uncover hidden costs and chart a path to plugging leaks:
- Review bank and credit-card statements for unfamiliar merchant names and recurring charges.
- Check app-store and payment-wallet subscriptions for unused or forgotten services.
- Monitor billing dates and set automated low-balance or upcoming-charge alerts.
- Compare current service rates with the original signup price to detect price creep.
- Assess your usage and perceived value for each recurring payment.
You may be surprised how many services you barely use or how automatic fees have crept higher over time. Approaching the audit with curiosity instead of guilt will keep you motivated and prevent overwhelm.
Common Leak Categories and Fixes
Once you’ve listed potential leaks, tackle each category with targeted strategies:
Streaming and digital subscriptions: Pause or cancel platforms you rarely use. Consolidate similar services or share family plans responsibly. Check usage reports to guide your decision.
Convenience and delivery fees: Batch errands or pick up in-store when possible to reduce rideshare and food-delivery costs. Use free shipping thresholds for online purchases and plan weekly errands to cut unnecessary trips.
Impulse purchases: Remove saved payment details, unsubscribe from retail newsletters, and impose a 24-hour waiting period on non-essential buys. This simple buffer often kills impulsive clicks.
Food waste and unplanned meals: Audit your pantry before shopping, plan flexible meals around existing staples, label items with use-by dates, and freeze surplus ingredients before they spoil. Meal-prep apps can help track what you already have.
Banking and service fees: Maintain a checking-account buffer, enable low-balance alerts, and simple, practical waste-reduction strategies like opting out of overdraft protection when appropriate or negotiating fee waivers with your bank.
Price creep on recurring bills: Review your insurance, mobile, and internet plans against competitor offers. Ask providers about promotional pricing, bundle discounts, or loyalty rates. Even a small percentage reduction can save dozens monthly.
Duplicate or overlapping services: Audit overlapping benefits such as credit-card travel protections versus standalone insurance or multiple cloud-storage subscriptions. Consolidate or downgrade plans without sacrificing essential coverage.
Buy-now-pay-later installments: Track instalment schedules and treat these plans like any other debt. Prioritize high-interest obligations and consider paying off a plan early to avoid hidden finance charges.
Redirecting Recovered Funds Purposefully
Recovering even $50 to $100 a month can create a meaningful buffer. Automate transfers to a high-yield savings account or apply the funds toward credit-card debt. Over time, those redirected dollars accelerate your progress toward financial goals.
Experts recommend building a three- to six-month emergency savings buffer. Plugging budgetary leaks develops habits that support ongoing surplus generation, feeding a virtuous cycle of security and growth.
Consider pairing your audit with cash-back portals, round-up savings apps, or loyalty rewards programs. These tools can amplify the impact of your leak plugging without drastic lifestyle changes.
Conclusion
Invisible spending leaks are not a moral failing; they’re an opportunity. By shining light on often unnoticed small, recurring expenses and making targeted adjustments, you can transform stealthy drips of outflow into a robust safety net.
Begin today by selecting one category, conducting a quick audit, and implementing a single change. Over weeks and months, these efforts will accumulate, empowering you with confidence that every dollar you earn works toward securing your future. Remember, financial resilience is a journey—each plugged leak builds a stronger tomorrow.