In a world that often equates financial success with windfalls or heroic decisions, it’s easy to overlook the everyday choices that truly shape our monetary well-being. Instead of obsessing over extreme frugality or waiting for a high income, financial discipline can be understood as repeatable behaviors that drive lasting results. By focusing on structured systems rather than one-off victories, anyone can build sustainable wealth.
Financial discipline is less about never spending and more about making intentional decisions aligned with clear priorities. It combines careful tracking, automation, strategic saving, and thoughtful investing. In this article, we’ll explore how ordinary habits, when repeated consistently, lay the foundation for financial resilience and long-term prosperity.
Despite nearly half of U.S. adults—49% in a 2025 Northwestern Mutual study—calling themselves "disciplined planners," only about 31% maintained a documented long-term plan. Meanwhile, a basic financial-literacy assessment found adults answered just 49% of questions correctly. These gaps underline that financial knowledge alone is not enough and must be paired with reliable systems and behaviors.
Defining Financial Discipline and Its Distinctions
At its core, financial discipline is a behavioral skill, not a personality trait. It’s the ability to align daily financial actions with long-term goals. Many confuse discipline with restriction, but the difference is profound:
Understanding this distinction helps shift mindset from deprivation to deliberate planning. True financial discipline builds present stability and future opportunity without the need for perfect execution.
Financial Awareness: The Foundation for Smart Choices
You cannot manage what you do not measure. The first step in any disciplined money system is developing clear awareness of your current situation. Experts recommend a monthly review that covers every aspect of your finances, including:
- Net income and cash flow timing
- Fixed and variable expenses
- Debt payments and interest rates
- Savings and investment contributions
- Irregular or annual expenses
- Discretionary spending patterns
Tracking for at least 30 days before adjusting your plan is crucial; this exercise is meant for diagnosis, not judgment. A simple calculation can reveal your capacity to grow:
Monthly surplus = Net income − Essential spending − Debt payments − Savings and investments
A negative surplus is not a failure; it’s a signal that your plan needs refinement. With accurate data, you can make informed adjustments rather than relying on guesswork.
Automate and Allocate: Making Good Choices Default
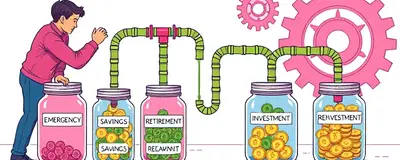
One of the most powerful tools in the disciplined planner’s toolkit is automation. By setting up consistent, automated transfers, you remove friction and ensure progress without constant intervention. Consider automating these flows:
- Bill payments and minimum debt repayments
- Emergency fund contributions
- Retirement account or employer plan deposits
- Investments in taxable accounts or education savings
By directing your income to critical areas first, you create a system that prioritizes long-term security over impulse purchases. Many Americans have adopted this approach: Northwestern Mutual’s 2025 Planning & Progress Study found that 49% of U.S. adults considered themselves “disciplined planners,” up from 45% in 2024.
Strengthening Resilience: Emergency Funds and Debt Management
Financial resilience is the ability to absorb shocks without derailing long-term progress. Emergency savings play a vital role. According to Federal Reserve data, 63% of adults could cover a $400 emergency with cash, savings, or a credit card paid off at the next statement. However, only 55% reported having three months of expenses set aside.
Other surveys show variation: FINRA Foundation research puts the share of adults with three months of savings at 46%, while Bankrate found 27% of adults had no emergency fund at all. These differences highlight the need for consistent planning rather than one-time efforts.
Debt management is equally important. In 2025, U.S. adults with personal debt carried an average balance of $21,500, down from $22,713 in 2024. While 64% prioritized paying down debt over saving, buy-now-pay-later services remain popular: 33% of adults used them for large purchases and 23% for routine items. Balancing debt repayment with accumulation of savings builds long-term financial well-being and reduces stress.
Investing for the Future: Harnessing Compound Growth
Once you have automated savings and established emergency buffers, the next step is long-term investing. The key is to create a diversified portfolio that reflects your goals, timeframe, and risk tolerance. Contributing regularly to tax-advantaged accounts and taxable brokerage accounts captures the power of compound interest.
Even modest annual returns, compounded over decades, can transform small regular investments into significant wealth. For example, a $200 monthly investment at 7% annual growth becomes over $350,000 in 30 years. This modest annual returns compounded over time effect underscores the value of consistency.
Financial resolution data suggests strong intent: 64% of respondents in Fidelity’s 2026 study considered a financial resolution, with saving more ranked highest at 44%, paying down debt at 36%, and spending less at 30%. Aligning these goals with your automated plan boosts follow-through and turns aspiration into reality.
Review and Adapt: Sustaining Your System
A robust finance system is not static. Life changes—raises, new family members, market shifts—and your plan must evolve accordingly. Schedule quarterly or semiannual check-ins to:
- Compare actual results versus your spending plan.
- Reassess priorities for saving, debt repayment, and investment.
- Update insurance, wills, and beneficiaries.
- Adjust automation settings for new goals.
This ongoing feedback loop ensures your system continues to serve your needs. As Allianz Life reported, many people know their worst habits—overspending, under-saving, or delaying debt payoff—but knowing alone isn’t enough. It’s the daily application of sound systems that creates lasting change.
Financial discipline is less about grand gestures and more about small, repeated choices over time. By focusing on awareness, intentional planning, automation, resilience building, and adaptive review, you transform money management into a sustainable system. The journey to long-term freedom and security begins not with scarcity, but with structure—and the confidence that comes from living by a well-designed plan.