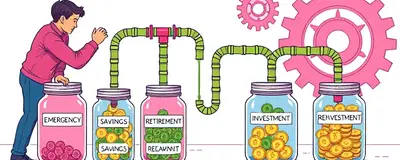
True prosperity goes beyond wages. It emerges when income becomes productive assets and optionality grows.
Rethinking Income, Assets, and Prosperity
Most people focus on income alone as the measure of success. In reality, there are five distinct components of financial well-being:
This article reframes wealth hacking as deliberate strategic action rather than a quick money grab. Unconventional paths carry risk and volatility, but they can lead to durable and resilient net worth when executed ethically and intelligently.
The Side-Hustle Economy: A Laboratory, Not Destiny
Surveys report between 27% and 47% of U.S. adults engaged in a side hustle last year. Intuit QuickBooks found 47% had secondary income, while Bankrate measured 27%. A Federal Reserve study noted 20% did gig work monthly. These figures vary by definition and methodology.
A side hustle that uses excess evenings for low returns may boost cash flow without adding significant equity. Median earnings hover around $200 per month, with averages of $885 to $1,242. For many, it’s necessity-driven, not wealth-driven.
A side hustle can evolve into a scalable business if it addresses a genuine customer problem, leverages distribution, and becomes repeatable. Otherwise it remains a labor-for-income model.
1. Build a High-Value Skill Stack
Skill stacking means combining ordinary skills into an uncommon and marketable package. Examples include:
- Writing plus search-engine optimization
- Design plus user research
- Coding plus industry knowledge
- AI tools plus domain expertise
By pairing multiple competencies, you gain pricing power above commodity rates and access to premium clients or employers. You become less dependent on any single income source and can transform services into products.
Key to wealth creation is linking skills to a real customer problem, a distribution channel, a repeatable offer, and a mechanism for saving and investing the profits.
2. Turn Freelancing into an Asset
Freelancing often serves as the first stage on the path to wealth hacking. Follow this progression:
- Sell personal labor at market rates.
- Specialize in a valuable niche problem.
- Raise prices through demonstrated expertise.
- Standardize and document your process.
- Outsource work to contractors or employees.
- Establish recurring contracts.
- Spin out the operation into an agency, software model, or course.
Transitioning from freelancer to agency owner shifts you from owning a job to owning a system. From there, creating a digital product or a licensing model leads to true asset ownership.
3. Entrepreneurship and Small-Business Ownership
Owning a business offers multiple wealth channels: operating profits, appreciation in value, tax advantages, and intellectual property rights. Business equity ranks as the second-largest category of family nonfinancial assets after home equity.
Data shows typical small-business founders had higher liquid wealth pre-launch. Those resources often provide the runway to grow operations. Yet entrepreneurship carries significant challenges:
- High failure rates and unstable income
- Debt exposure and personal guarantees
- Customer concentration risks
- Regulatory and management burdens
For many, combining stable employment with disciplined investing may yield more consistent progress toward prosperity than starting a business from scratch.
4. Acquire and Improve an Existing Business
Buying an established company can be more efficient than founding one. Targets include local service firms, niche e-commerce sites, and small software businesses owned by retirees.
Wealth hacking in acquisitions relies on improvement rather than invention:
- Optimizing pricing and scheduling
- Implementing digital marketing
- Automating administration
- Introducing recurring revenue offerings
Perform rigorous due diligence on revenue quality, customer concentration, working capital needs, legal liabilities, and whether earnings reflect genuine profits or the owner’s unpaid labor.
5. Use Artificial Intelligence as a Productivity Multiplier
AI adoption has become widespread among entrepreneurs, with HSBC reporting plans to allocate 21% of turnover to AI investments. But AI alone doesn’t guarantee wealth.
Define AI advantage as better processes plus human judgment combined with distribution and ownership. Practical applications include automating research, generating first drafts, improving customer support, and compressing the time to test ideas.
Owning an AI-enabled product or process, rather than using AI solely to accelerate freelance tasks, elevates your position from labor to asset owner.
Charting a Path to Durable Wealth
Wealth hacking is the ethical and deliberate use of ownership, leverage, technology, asymmetric opportunities, and unconventional careers to accelerate net worth growth. It demands careful planning, persistent execution, and a willingness to absorb risk.
The most successful practitioners convert income into productive assets: equity stakes, intellectual property, automated systems, and scalable businesses. They understand that true prosperity blends financial security with autonomy, time flexibility, and health.
By embracing the concepts of skill stacking, asset ownership, strategic acquisitions, and AI leverage, you can build resilience against economic shocks and create a foundation for lasting wealth. The journey won’t be easy or guaranteed, but with disciplined execution, you can outpace the limits of wages alone and achieve a life of genuine autonomy and abundance.